Background of the case
In a recent ruling, the Ahmedabad Income Tax Appellate Tribunal, (hereinafter referred to as “the Tribunal” or “ITAT”), in the case of Sun Pharma Laboratories Limited1 (“the Assessee” or “the Company”), adjudicated upon the allowability of a short-term capital loss arising from the transfer of a partnership interest in a limited liability partnership to an entity alleged to be a related party.
While the ruling involved multiple issues like deduction under sections 80-IB and 80-IE, disallowance under section 14A read with Rule 8D and many more, this summary is confined only to the central dispute concerning whether the assignment of the Assessee’s partnership interest in Silverstreet LLP to Suraksha Buildwell LLP, which resulted in a claimed loss of approximately INR 263.69 crore, constituted a genuine capital loss computed in accordance with Sections 45 and 48 of the Income-tax Act, 1961 (“the Act”), or whether it amounted to a fictitious, paper loss engineered within a group structure.
Facts of the case:
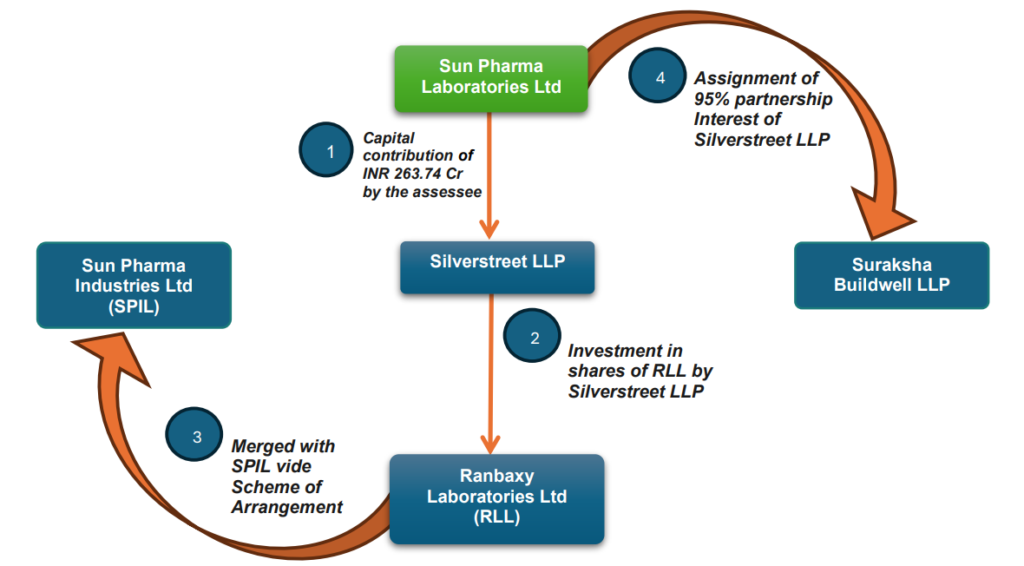
- The Assessee, a pharmaceutical manufacturing company, contributed capital aggregating to approximately INR 263.74 crore in Silverstreet LLP during FY 2013-14.
- Silverstreet LLP, in turn, invested in equity shares of Ranbaxy Laboratories Limited (“RLL”).
- Pursuant to a court-approved Scheme of Arrangement, RLL got merged with Sun Pharma Industries Limited (SPIL). Pursuant to this merger, all shares of RLL held by SPIL, its subsidiaries and LLPs (including Silverstreet LLP) stood cancelled without allotment of any corresponding shares of SPIL, thereby fully eroding the value of Silverstreet LLP.
- During FY 2015-16, the Assessee assigned its entire partnership interest in Silverstreet LLP to Suraksha Buildwell LLP for a consideration of INR 5 lakhs, by a duly executed Deed of Assignment effected in accordance with Section 42 of the Limited Liability Partnership Act, 2008 (“LLP Act”).
- The Assessee computed a short-term capital loss of approximately INR 263.69 crore under Sections 45 and 48 of the Act, treating the capital contributed as the cost of acquisition of the partnership interest.
- The Assessing Officer (“AO”) disallowed the loss in its entirety, holding the transaction to be a colourable device intended to generate an artificial capital loss, on the ground that both the Silverstreet LLP and Suraksha Buildwell LLP were entities controlled directly or indirectly by promoters and family members of the Sun Pharma Group.
- The AO also took the position that the investment in the shares of RLL had substantially remained within the same group, and that the transaction resulted only in book entries without any genuine commercial loss. He further held that the cost of acquisition ought to be treated as Nil, since the book value of the Assessee’s investment had become Nil after cancellation of the RLL shares.
- The CIT(A) upheld the disallowance of the AO, confirming that all entities involved were either directly or indirectly under the control of the Sun Pharma Group and that the transaction was intended solely to create an artificial capital loss.
- Aggrieved by the above order, the assessee preferred an appeal before the Tribunal in respect of the said dispute.
Key Issues
- Whether a partnership interest held in a limited liability partnership constitutes a “capital asset” within the meaning of Section 2(14) of the Act and whether its assignment under Section 42 of the LLP Act constitutes a “transfer” under Section 2(47), thereby attracting the charge to capital gains under Section 45?
- Whether, in the absence of a valuation report from either the Assessee or the Revenue in respect of the partnership interest transferred, the disallowance of the short-term capital loss of approximately INR 263.69 crore as a fictitious and artificial loss is sustainable?
Key Takeaways
- Partnership interest in an LLP as a capital asset and the scope of “transfer”
- The Tribunal held that the partnership rights held by the Assessee in the Silverstreet LLP constitute “property of any kind” and therefore a capital asset within the meaning of Section 2(14) of the Act, which is further reinforced by Section 49(2AAA) of the Act, which expressly recognises rights of a partner under Section 42 of the LLP Act as capital assets.
- The Tribunal further held that since the assignment was effected by a duly executed Deed of Assignment for valuable consideration in accordance with Section 42 of the LLP Act, it squarely falls within the expression “transfer” under Section 2(47) of the Act, and the provisions of Sections 45 and 48 become applicable in their ordinary statutory meaning.
- Disallowance of capital loss without a valuation report is unsustainable
- The Tribunal noted that neither the AO nor the Assessee had followed proper valuation mechanisms in respect of transfer of partnership interest of Silverstreet LLP to Suraksha Buildwell LLP.
- The Tribunal held that where a transaction is alleged to be between related parties, valuation becomes more relevant, and remanded the matter back to the AO with the following directions:
- to call for pre-merger and post-merger financial statements of the amalgamated and amalgamating companies in order to understand the accounting treatment given as a result of the merger,
- to call for accounts of the Silverstreet LLP as on the date of transfer of interest in Silverstreet LLP.
- Further, the Tribunal directed the Assessee to bring on record a valuation report from an authorised person valuing the partnership interest in the Silverstreet LLP as on the date of transfer, so as to arrive at the fair valuation of the interest and compute the actual gain or loss arising from the transaction.
Conclusion
The Tribunal affirmed that a partnership interest in a limited liability partnership constitutes a capital asset under Section 2(14) of the Act, and that its assignment in compliance with Section 42 of the LLP Act constitutes a transfer within the meaning of Section 2(47), attracting the computation provisions under Sections 45 and 48. Given the complete absence of a valuation report on record and the failure of both parties to apply any prescribed valuation methodology, the Tribunal remanded the matter back to the Assessing Officer for fresh adjudication.
- ITA No.1733/Ahd/2024 and ITA No.1742/Ahd/2024 ↩︎
Leave A Comment